Quick Guide to Buying a Condo in Singapore (2025)
*Skip the content and connect with a representative to rent, buy or sell property, here.
This quick-start guide covers buying a private condo in Singapore, the eligibility, core costs, and more—for Singapore Citizens, PRs and foreign buyers.
For more comprehensive purchasing insights, read our New Launch vs. Resale Condo Guide.
Not ready to buy and looking to rent? Read our Renting in Singapore Guide.
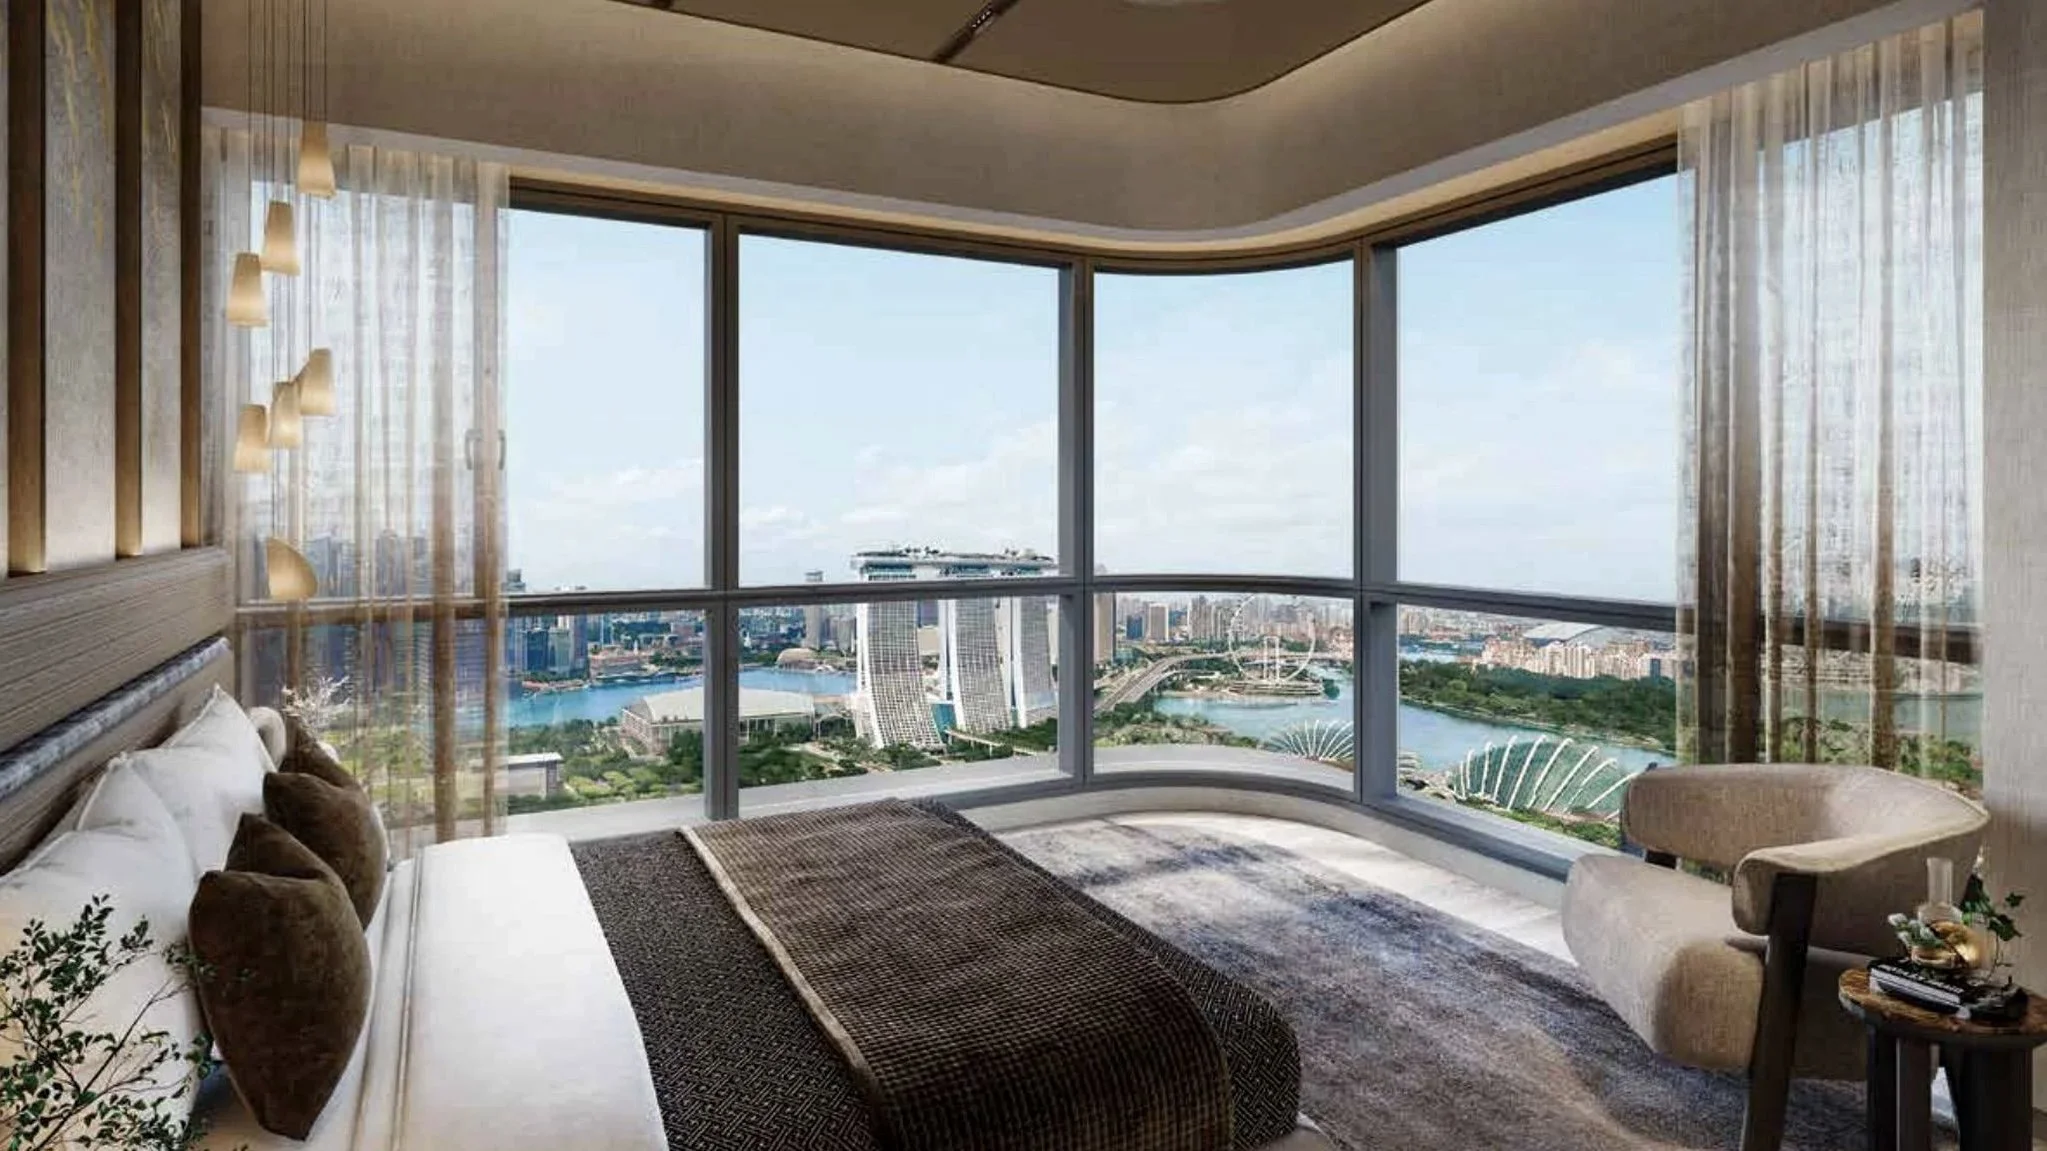
One Marina Gardens, Singapore
Eligibility
Singapore Citizens (SCs): Eligible to buy private condominiums.
Permanent Residents (PRs): Eligible to buy private condominiums.
Foreigners (non-PR): Eligible to buy private condos (landed properties needs separate approval); higher duties may apply.
Tip: If you’re upgrading from an HDB → condo, we can help you plan timing/financing to avoid unnecessary duties.
Expenses you should plan for
Buyer’s Stamp Duty (BSD): Progressive tax based on purchase price/market value (tiered).
Additional Buyer’s Stamp Duty (ABSD): Varies by residency status and how many homes you already own in Singapore:
SC: 1st property 0%
PR: 1st property 5%
Foreigner: 60% (any residential purchase)
Other: Legal/conveyancing fees, valuation, loan/admin fees, insurance, moving/renovation.
Agent fees: Buyers usually don’t pay a fee; case-by-case.
Ownership, resale & taxes
MOP (minimum occupancy period): No MOP for private condos.
Seller’s Stamp Duty (SSD): Applies if sold within 4 years of purchase: Year 1: 16% · Year 2: 12% · Year 3: 8% · Year 4: 4%; >4 years: 0%.
Capital gains: Generally no capital gains in Singapore; gains may be taxable only if the IRAS deems you’re trading in property.
Rental income: Taxable; property tax also applies.
Tenure & lease basics (freehold vs leasehold)
Tenure types you’ll see: Freehold, 999-year leasehold (behaves like freehold), and 99-year leasehold (most new launches).
Tenure is uniform: You don’t choose tenure type unit-by-unit, the whole development sits on one land title.
Executive Condominiums (ECs): always 99-years; they “privatize” after 10 years but the lease length doesn’t change.
Financing basics
TDSR (Total Debt Servicing Ratio): Total monthly debt (including new mortgage) is ≤ 55% of gross monthly income (pre-tax).
LTV (Loan-to-Value) & minimum down-payment:
No existing housing loan: up to 75% LTV → 25% down (min 5% cash, balance cash/CPF-OA).
1 existing housing loan: up to 45% LTV → 55% down (min 25% cash).
2+ existing loans: up to 35% LTV → 65% down (min 25% cash).
If tenure >30 yrs or extends past age 65 → lower LTV tier (e.g., 55% for first loan) and higher min cash (10%).
CPF usage: Singapore Citizens/PRs can use CPF-OA for part of down-payment and stamp/legal fees; foreigners generally cannot (cash/own funds only).
The Liu Organization – Singapore’s Trusted Property Agents
Have more questions? We specialize in helping you to buy, rent or sell property in Singapore whether for residence or investment.
📩 Contact us via this form to begin your condo search today.
